The Real Estate Agent’s No-BS Guide to Interest Rates: What to Say When Your Clients Ask
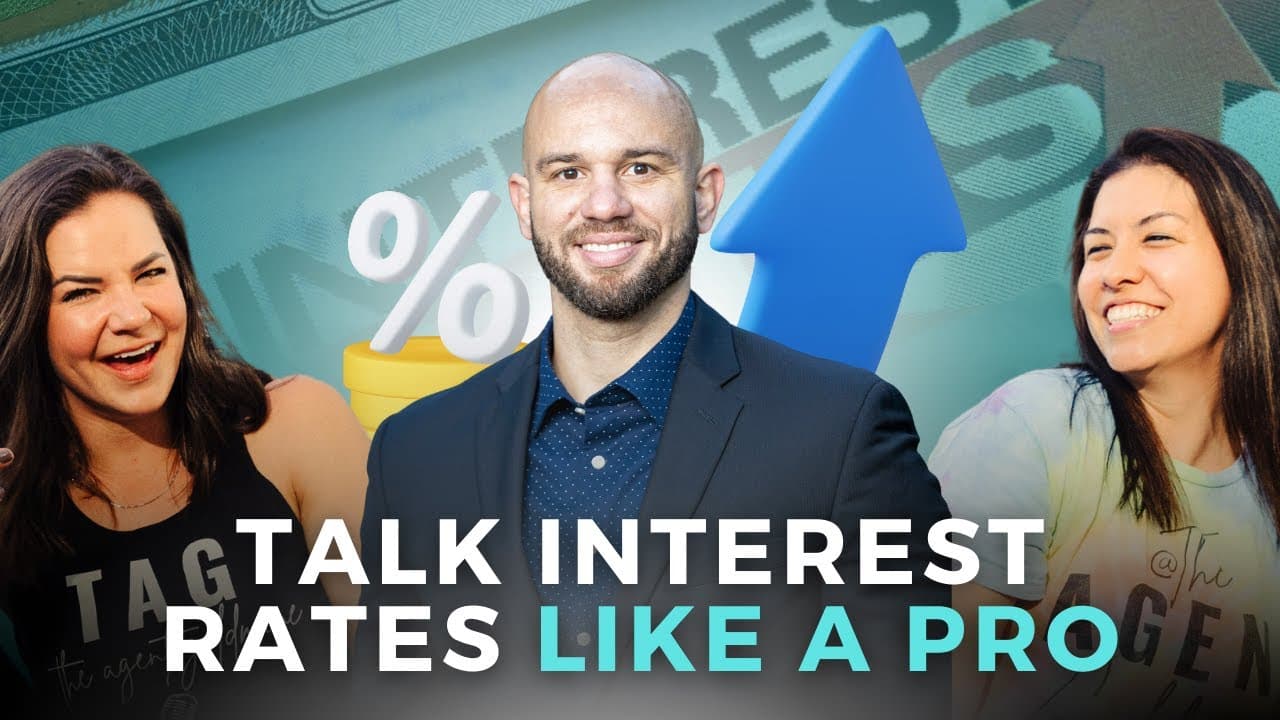
Have you ever had a client look you dead in the eye, ask what interest rates are going to do next month, and you immediately felt a cold sweat breaking out? If you’ve ever felt underprepared or straight-up dumb when the topic of interest rates comes up, you are in luck. In this episode of the Agent Goldmine, we brought on our absolute G of a best friend, Michael Glaspie—an Army Green Beret turned real estate entrepreneur and fractional CFO—to make interest rates fun, easy, and highly actionable for your business.
The Federal Reserve 101: Where Do Interest Rates Actually Come From?
Most people sit around saying things like, “Oh, the rates are definitely going to drop after the election.” But when we sat down with Mike, he threw some major truth bombs about where these numbers actually originate. Spoiler alert: It has almost nothing to do with who is sitting in the Oval Office.
To understand today’s lending system, we have to rewind to 1910 when the Federal Reserve (our nation’s central bank) was conceived, officially launching around 1913. Before the Fed, commercial banks were like the Wild West—lending money to each other at whatever crazy rates they wanted, which often crushed smaller regional banks.
The Fed was created to regulate the relationships between these commercial banks by setting the federal funds rate. This is the baseline rate at which Bank of America can lend money to Wells Fargo.
The Art of Bank Arbitrage
How do commercial banks actually make money? They do it through a process called arbitrage.
Essentially, banks borrow money (either from our personal checking accounts or from other banks) at a low baseline rate and lend it out to buyers at a higher rate. They collect that spread in the middle as pure profit.
“Everything is fake! Banks borrow money at one rate, lend it out at a higher rate, and actually lend out our deposits to multiple people at the same time. It's a massive chain of arbitrage.”
Why Our Money is 'Fake' (The Shift to Fiat Currency)
During our chat, Mike took us on a quick history lesson back to the Great Depression of the 1930s. When the economy collapsed, the Federal Reserve kept interest rates high, which meant nobody could borrow money, leading to massive unemployment and foreclosures.
The Fed quickly realized they have a giant dial to control the economy: they can slow things down by jacking up rates, or speed things up by slashing them (known as quantitative easing).
This dial got even wilder in 1974 when the United States officially went off the gold standard. Since then, the U.S. dollar has been a fiat currency—meaning it is backed by absolutely nothing but our word and global influence. Because of this, the government can essentially print money to bail out the economy during crises like 2008 or COVID-19, which heavily impacts inflation and interest rates.
The Anatomy of a Mortgage Interest Rate
When the Federal Reserve changes its baseline rate, how does that translate to the 7% or 8% rate your homebuyer sees? It all comes down to the prime rate and basis points.
What is the Prime Rate?
The prime rate is the interest rate banks charge their absolute best, highest-credit, most reliable borrowers. While there is no universal standard, most banks calculate their prime rate by taking the Federal Reserve rate and tacking on a margin of about 3%.
If the Fed rate is 4%, the prime rate will hover around 7%. From there, the average everyday borrower will get charged Prime plus 1% or 2%, depending on their debt-to-income ratio and credit score.
What are Basis Points?
If you want to sound like a sophisticated financial wizard in front of your clients, stop saying “half a percent” and start using the term basis points. One full percentage point equals 100 basis points. So, if a lender tells you rates dropped by 50 basis points, they mean they dropped by half a percent.
What Actually Influences Interest Rates?
If the upcoming election isn't the primary driver of interest rates, what is? Mike broke down the true macroeconomic catalysts that the Fed looks at when adjusting monetary policy:
- Consumption Patterns: How much are everyday consumers spending on goods and services?
- Unemployment Rates: Is the labor market too tight or too weak?
- Exchange Rates: How is our currency performing against foreign currencies?
- Black Swan Events: Unpredictable, world-altering events (like the Great Depression, the 1970s oil crisis, the 2008 housing crash, or the COVID-19 pandemic) are what trigger sudden, massive rate drops.
Unless we experience a catastrophic global event, rates are highly unlikely to plummet back to the 3% or 4% range anytime soon. We need to help our clients buckle up and get comfortable with the current normal.
How to Handle Tough Client Interest Rate Questions
As agents, we have to stop giving the deer-in-the-headlights look. Here are two of the most common client objections and exactly how Mike suggests you handle them.
Objection 1: “I’m going to wait until interest rates drop to buy a home.”
When a client says this, your instinct might be to ask, “Why do you want to wait?” According to communication experts, asking “why” forces the client to defend and cement their belief system, making them even harder to convert.
Instead, validate them and present the macroeconomic reality:
“I completely understand wanting a lower payment. But the truth is, interest rates are driven by the global economy, and right now there are no indicators that rates will drop significantly anytime soon. If you wait, you are gambling on an unpredictable future. It’s always smarter to buy the home now and refinance later when rates eventually shift.”
Objection 2: “What do you think interest rates will do in the future?”
Be honest and direct. Do not try to guess or promise a rate drop to close a deal.
Try this script: “To be honest, I expect rates to stay fairly stable in this current range for the long haul. We’ve stabilized after the pandemic, and unless there’s a major global crisis, we won't see dramatic drops. Now is the time to build your budget around today's reality.”
The Truth About Rate Buy-Downs and Down Payment Assistance
When rates are high, buyers start looking for creative loopholes. However, you need to protect your clients from products that sound too good to be true.
Are Rate Buy-Downs Worth It?
Lenders love promoting rate buy-downs because it increases their upfront yield. But for the average homebuyer, paying thousands of dollars upfront to lower their rate by a point rarely makes financial sense.
The average lifespan of a mortgage before a homeowner sells or refinances is only 5 to 7 years. When you do the math, the buyer rarely reaches the break-even point to recoup the upfront cash they spent buying down those points. Keep your client's cash in their pocket instead.
The Hidden Traps of Down Payment Assistance Programs
We see a lot of programs out there claiming to offer “free” grants or down payment assistance. As the saying goes, if it sounds too good to be true, it probably is.
Many of these assistance programs come with major fine print and golden handcuffs. For example, some programs forbid the homeowner from selling the property for a set number of years, or require the entire grant to be paid back with heavy interest upon sale. If life happens—like a sudden divorce or job relocation—your client could find themselves trapped in a house they are legally forbidden to sell.
The Ultimate Agent Financial Resource List
If you want to nerd out and build your financial confidence so you can speak to high-C analytical clients, here are the exact resources Mike recommends:
- FederalReserve.gov: Go straight to the source for policy changes and official announcements.
- FRED (Federal Reserve Economic Data): A highly visual, easily digestible database hosted by the St. Louis Fed that shows historical rate charts.
- Investopedia: The absolute best place to look up financial jargon and get simple, clear definitions.
- NPR’s Planet Money Podcast: Great for learning economic concepts through engaging, story-based episodes.
- The Creature from Jekyll Island (Book): A deep, analytical dive that exposes the flaws and history of the Federal Reserve system.
Take Control of Your Financial Business
As agents, we are great at slinging deals, but many of us are a hot mess when it comes to our own business finances. If your books are non-existent, you have no clarity on your financial future, or you're ready to scale your business like a machine, you need a professional team in your corner.
Mike and his wife, Yesenia, run G2 Business Solutions. They specialize in helping real estate professionals with bookkeeping, tax prep, tax strategy, and fractional CFO services. They have completely revolutionized how we look at our own personal business numbers, providing monthly reports and clear financial guidance so we always know where our money is going.
If you’re ready to get your financial house in order, head over to G2BusinessSolutions.com or find Michael Glaspie on Instagram!
That's all for this breakdown. To hear more real estate strategies from top producers, tune in to the Agent Goldmine podcast. Ready to scale your operations? You can book a consultation with us at Five Pillars Nation anytime.